Use this no tax on tips calculator to estimate your deduction. The One Big Beautiful Bill Act (Public Law 119-21, signed July 4, 2025) created a federal income tax deduction for qualified tips. It is often called “no tax on tips”. This no tax on tips calculator estimates how much of your tip income you can deduct for tax years 2025 through 2028, after the income phaseout, and roughly how much federal income tax that saves.
All figures on this page come from IRS guidance and the new Schedule 1-A (Form 1040).
What the tips deduction is
It is a deduction of up to $25,000 a year of qualified tips. It lowers your taxable income, but the tips still count in your gross income first. You can claim it whether you take the standard deduction or itemize. It does not remove Social Security and Medicare (FICA) tax, or state income tax unless your state follows the federal rule.
Who qualifies
- Employees and self-employed people who receive tips in an occupation on the IRS list of jobs that “customarily and regularly” received tips on or before December 31, 2024 (see IRS.gov/TippedOccupations).
- The tips must be voluntary cash or charged tips from customers, or from tip sharing. Mandatory service charges do not count.
- The tips must be reported on a W-2, a 1099 or another statement, or by you on Form 4137.
- You must have a Social Security number valid for work. If you are married, you must file jointly.
- Self-employed people in a specified service trade or business (SSTB) are excluded, and so are employees of an SSTB employer. For the self-employed, the deduction cannot exceed net income from the business that earned the tips.
How to use the no tax on tips calculator
- Enter your total qualified tips for the year (W-2 box 7 and other reported tips).
- Enter your MAGI. For most people this is the AGI on Form 1040, line 11.
- Choose your filing status.
- Optionally, enter your marginal federal tax rate to see the estimated tax saving.
The formula
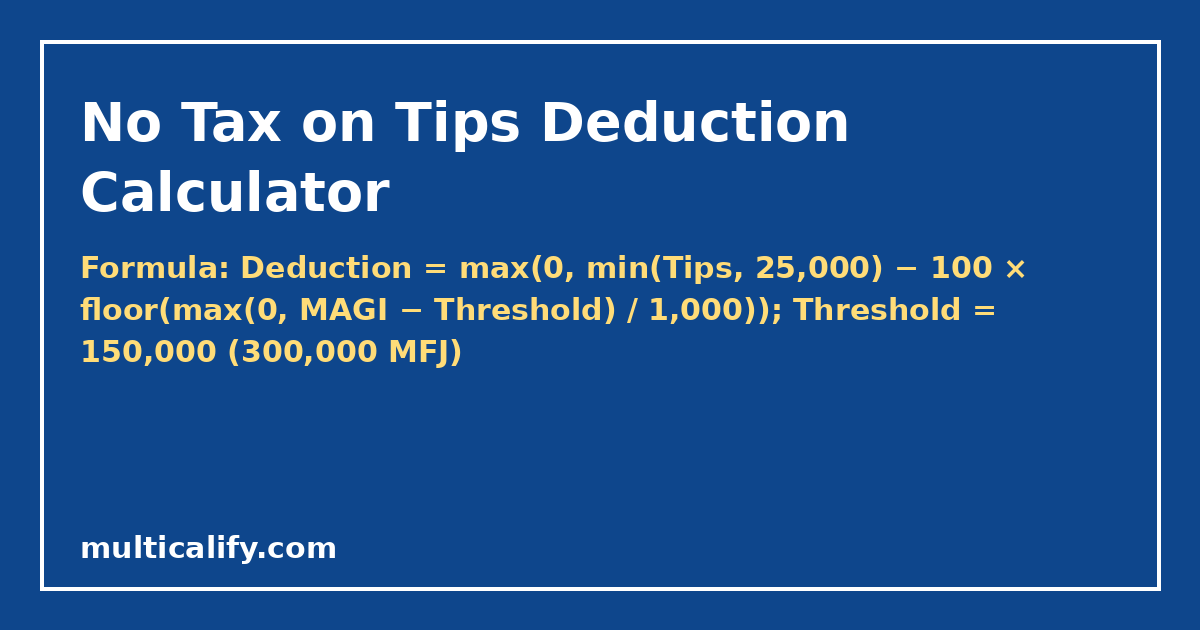
Step 1: Base = lesser of qualified tips or $25,000.
Step 2: Excess = MAGI − $150,000 ($300,000 if married filing jointly). If zero or less, there is no reduction.
Step 3: Reduction = $100 × (Excess ÷ $1,000, rounded down to a whole number).
Step 4: Deduction = Base − Reduction, but not less than $0.
Tax saving ≈ Deduction × your marginal federal rate.
Worked examples
Example 1: server, single
Jess earns $32,000 in wages plus $18,000 in reported tips. Her MAGI is $50,000, well under $150,000. She can deduct all $18,000. In the 12% bracket, that saves about $2,160 in federal income tax.
Example 2: high-earning bartender couple
Sam has $30,000 of tips. The couple’s joint MAGI is $312,400. Base = $25,000 (the cap). Excess = $12,400, which rounds down to 12 thousands. Reduction = 12 × $100 = $1,200. Deduction = $23,800. In the 24% bracket, that saves about $5,712.
Rules and limits
| Rule | Amount / detail |
|---|---|
| Tax years | 2025 – 2028 |
| Maximum deduction | $25,000 per return |
| Phaseout starts (MAGI) | $150,000 single / $300,000 joint |
| Phaseout rate | $100 per full $1,000 over the threshold (partial thousands ignored) |
| Itemize required? | No: available with the standard deduction |
| Married filing separately | Not allowed |
| FICA / payroll tax | Still owed on tips |
| Where claimed | Schedule 1-A, Part II |
Common mistakes
- Counting service charges. Automatic gratuities on large parties are wages, not qualified tips.
- Thinking tips become tax-free. FICA still applies, and the deduction is capped.
- Filing separately. Married couples must file jointly to claim it.
- Not reporting cash tips. Unreported tips do not qualify. Report them to your employer, or on Form 4137.
- Mixing it up with the overtime deduction. The overtime deduction is separate ($12,500, or $25,000 joint) and has its own rules.
Tips for tipped workers
- Keep a daily tip log, or use your employer’s POS reports, so your total matches your W-2.
- Check that your job is on the IRS tipped occupations list before counting on the deduction.
- Recheck your W-4 withholding. A lower tax bill may mean you can withhold less.
- Check your state’s rules. Many states do not follow this federal deduction.
How the deduction fits into your tax return
The tips deduction is taken after AGI, on Schedule 1-A, so it lowers taxable income without changing your AGI. This matters because many other benefits are based on AGI or MAGI. Your eligibility for the Earned Income Tax Credit, the premium tax credit, and the student loan interest deduction is still worked out on your income including tips. In the same way, the phaseout for this deduction uses MAGI that already includes the tips you are deducting.
You can claim the tips deduction and the overtime deduction in the same year if you have both. A server who also works overtime hours can use both parts of Schedule 1-A, each with its own cap.
Records to keep
- Your W-2 (box 7 for Social Security tips, and any new box or code the employer uses to report qualified tips and occupation).
- Form 4070 tip reports or the employer’s app records.
- Form 4137 if you reported unreported tips yourself.
- For the self-employed: 1099-K or 1099-NEC records showing which payments were tips.
For 2025, the IRS gave transition relief because employers did not yet have a box for qualified tips. In that case, use your best records and keep them for at least three years.
Our unique angle: rounding the way the form does
Many online tools phase the deduction out smoothly at 10%. Schedule 1-A divides the excess over the threshold by $1,000 and drops any fraction before multiplying by $100. So a couple $999 over the line loses nothing. The car loan interest deduction does the opposite: it rounds up. Our calculator follows each line of the form exactly, so your result matches what you will file.
Last reviewed: October 2026
Bookmark this no tax on tips calculator to rerun your numbers whenever your situation changes.
Results from this no tax on tips calculator are estimates, so check them against official IRS guidance. You can rerun the no tax on tips calculator whenever your tip income changes.
Related: income tax calculator · senior bonus deduction calculator · SALT deduction cap calculator · car loan interest deduction calculator · tip calculator.